Buying a house can feel like a series of hurdles. You find a place you love, make an offer, negotiate with the seller, get through the inspection, secure financing, and finally start counting down to closing day.
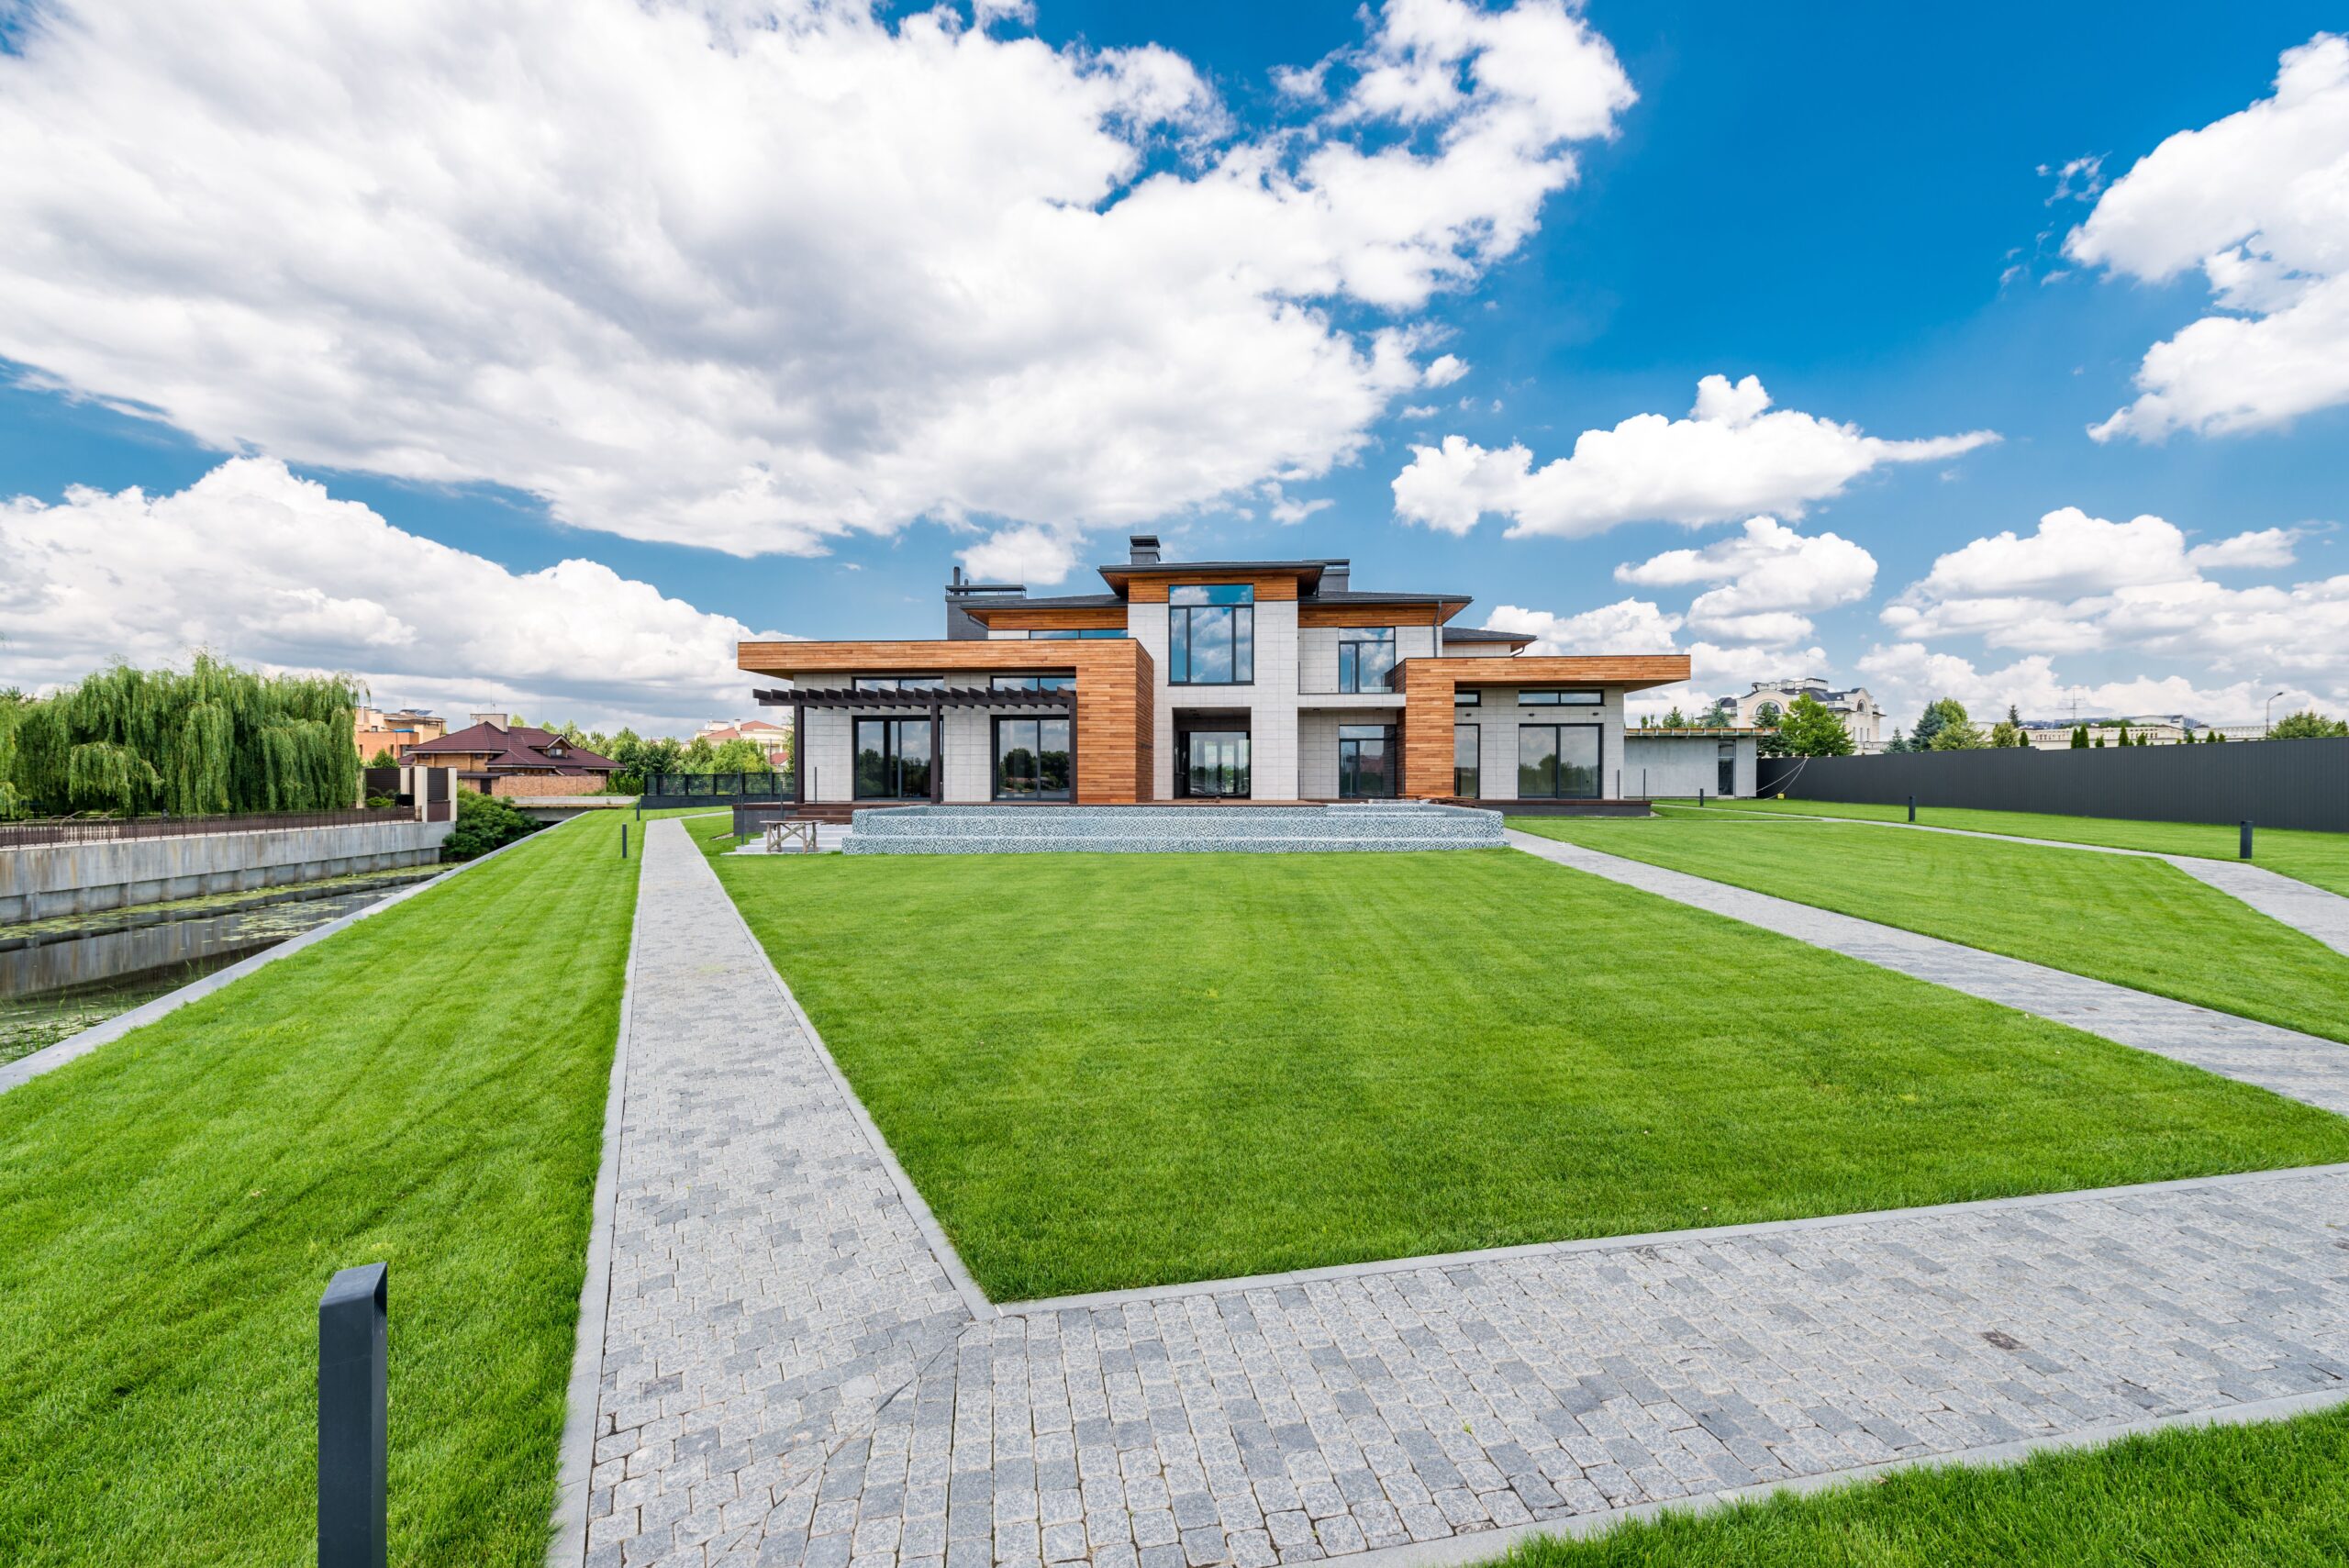
One buyer thought the hard part was behind them. Their offer had been accepted on a home listed for $1.025 million, and they were under contract for $1 million. With only one week left before closing, they were nearly ready to get the keys.
Then the appraisal came back.
The home was valued at $925,000, which was $75,000 below the agreed purchase price. The buyers had enough money to cover the gap, but they were already spending at the very top of their budget. Suddenly, the house they’d been excited to buy came with a much bigger financial question.
A low appraisal changed the entire conversation
An appraisal below the agreed purchase price doesn’t automatically mean a home is overpriced or that the buyer is making a mistake. An appraisal is an estimate of value based on available information, not a promise of what the property will sell for in the future.
Still, a $75,000 gap was too much for these buyers to ignore. They loved the home and weren’t ready to walk away, so they went back to the sellers with an offer of $950,000.
That was still $25,000 above the appraised value, but the sellers wouldn’t budge from the original $1 million price.
Related: Home Inspection Reveals Rotting Wood Hidden Beneath Fresh Paint
They tried to find a middle ground
The buyers weren’t ready to give up. They eventually raised their offer to $975,000 and were open to discussing other ways to make the purchase work, including asking the sellers to contribute toward buying down their mortgage rate.
The sellers remained firm at $1 million.
Their real estate agent even offered to cut her commission in half to help save the deal. That would have reduced the cost by only about $5,000, though, leaving the buyers with a much larger financial gap to consider.
Related: Problems Your Home Inspector May Not Find During a Walkthrough
Being able to afford something doesn’t mean you’re comfortable paying for it
This is probably the part many homebuyers can relate to. The buyers said they could cover the difference, but the purchase was already stretching their budget.
There’s a difference between having enough money to close on a house and having enough left over to feel financially secure afterward. Homeownership brings ongoing costs, from routine maintenance to unexpected repairs. Spending more cash than planned at closing can leave less room for those expenses.
A buyer might technically be able to afford a higher price and still decide the trade-off isn’t worth it.
Related: Open Houses Can Help Sell Your Home, but There’s a Catch
Walking away gets harder once you’ve pictured yourself living there
It’s hard to stay practical after you’ve fallen in love with a home. By the time closing day is only a week away, you may have already pictured where your furniture will go, what you’ll update, and what everyday life in the house will look like.
Walking away can feel like losing something you already considered yours. That emotional investment can make it harder to step back and look at the numbers without thinking about everything you might be giving up.
They ultimately walked away
After the sellers rejected their $975,000 offer, the buyers decided they weren’t comfortable taking on the added financial risk. They used their appraisal contingency to end the contract.
It wasn’t an easy choice, but the experience did leave them with something useful. They had found a community where they genuinely wanted to live, so they could keep looking for another home in the same area.
Related: 7 Forgotten Corners in Your Home That Could Store So Much More
There isn’t always a clear right answer
A low appraisal doesn’t mean every buyer should walk away. Paying more than an appraised value may still make sense depending on the property, local market, comparable sales, available cash, and how long the buyer plans to stay.
The important question is what paying the difference would mean for the buyer’s finances. Having another $75,000 available doesn’t automatically make spending it a wise decision, especially if the original purchase price was already at the limit of their budget.
For these buyers, the answer was to let the house go. They loved the property, but they weren’t willing to ignore their concerns just to make it to closing day.
Sometimes the house you want and the deal you’re comfortable accepting are two different things.